How to Plan and Pay for Long-Term Care
Most of us plan for retirement income but assume we’ll stay healthy. Yet about seven in ten people who reach 65 will need some long-term care, and a nursing home can top $100,000 a year. The dangerous myth is that Medicare pays for it — it doesn’t. Here is how to plan and pay for long-term care: the real costs, how Medicaid and insurance work, and the ways to fund it before you need it.
The long-term care risk nobody plans for#
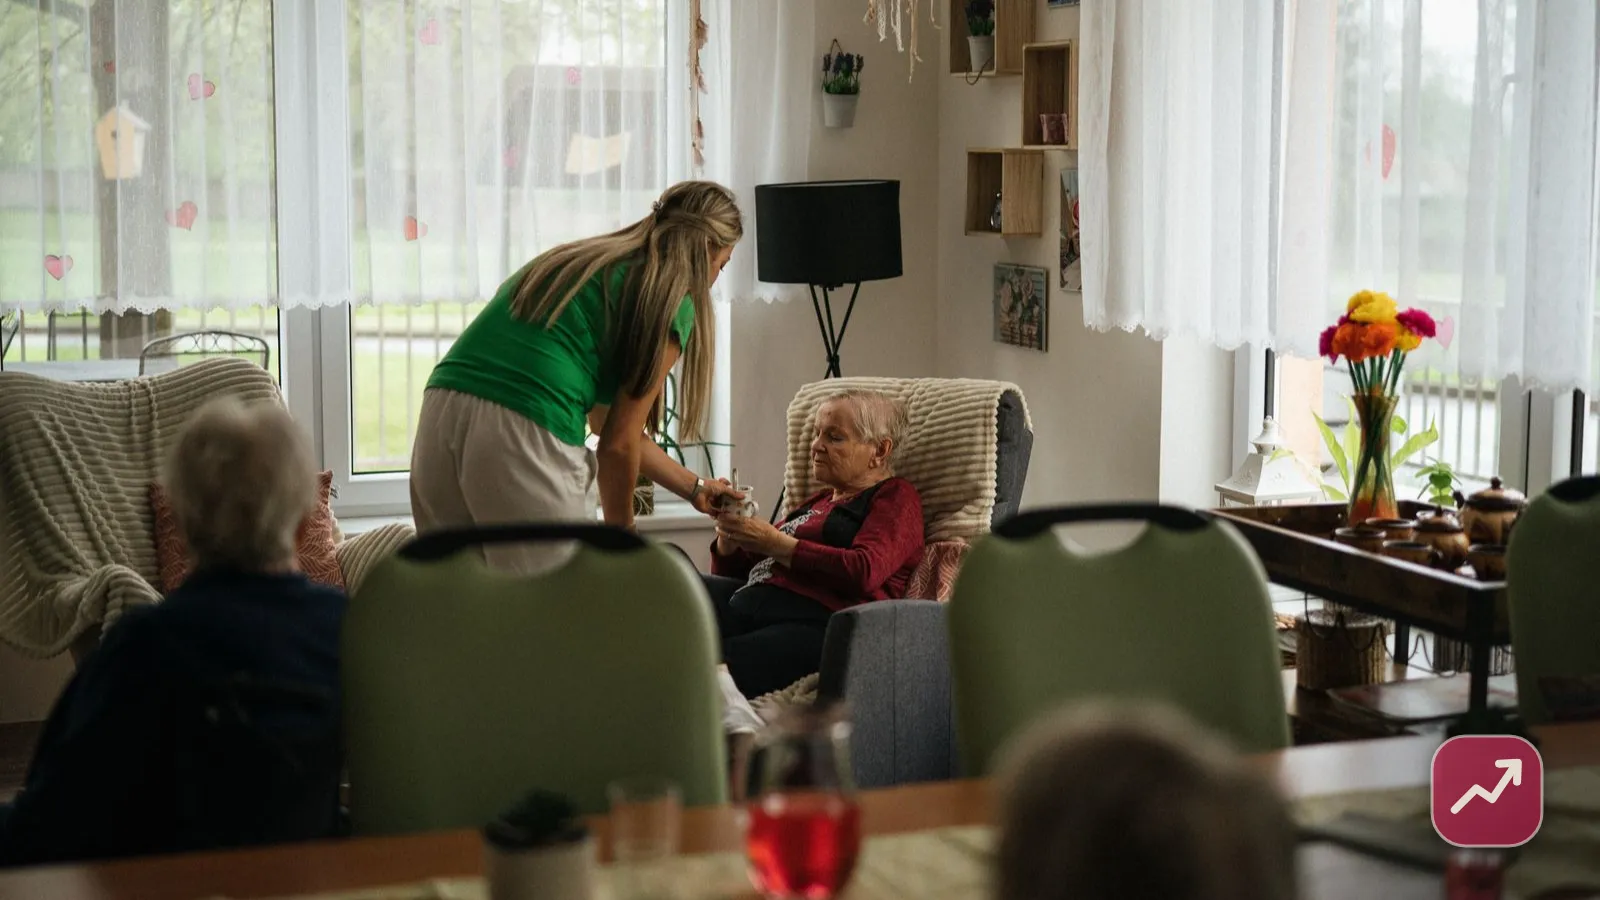
Most of us plan for retirement income but quietly assume we will stay healthy. Yet roughly seven in ten people who reach 65 will need some form of long-term care — help with everyday activities like bathing, dressing, or eating — at some point before they die. It is one of the biggest, and least planned-for, financial risks of later life, and the cost can run into six figures a year. Knowing how to pay for long-term care before you need it is what keeps it from wiping out a lifetime of savings.
The reason it catches families off guard is a widespread myth: that Medicare, or "the government," will simply cover it. Mostly, it will not. So the money has to come from somewhere — insurance, your own savings, family, or a government safety net that only kicks in once you are nearly broke.
This guide explains what long-term care actually costs, why Medicare does not pay, how Medicaid and long-term care insurance work, and the realistic ways to plan ahead. It also looks at Canada. As always, this is general education, not financial or medical advice — confirm the current rules where you live.
- ~70% of 65-year-olds will need some long-term care.
- Medicare doesn’t cover ongoing custodial care.
- Costs can top $100,000/year for a nursing home.
- Plan in your 50s — options shrink and cost more with age.
What long-term care actually costs#
The numbers are sobering. A private room in a nursing home now averages well over $100,000 a year in the US, with a semi-private room not far behind. Assisted living runs around $5,000 to $6,000 a month, and even bringing a home health aide into your own home costs roughly $30-plus an hour, which adds up fast once you need daily help.
Care can last a few months or many years, and dementia in particular can mean a decade of expensive support. Because the bills are so large and so open-ended, long-term care is less a routine expense than a catastrophic risk — the kind you plan for precisely because you hope it never arrives.
The big myth: Medicare doesn’t cover it#
Here is the single most important thing to understand: Medicare does not pay for long-term custodial care. It covers short-term skilled care — a limited stint of rehab after a hospital stay, up to about 100 days — but not the ongoing, non-medical help with daily living that "long-term care" really means. Assuming otherwise is the mistake that derails the most retirement plans. The distinctions are set out in the overview of long-term care.
That leaves four realistic ways to pay: out of your own savings, through long-term care insurance, from family caregiving, or via Medicaid — the government program that does cover it, but only after you have spent down almost everything you own. Most people end up using a mix, and the earlier you plan, the more control you keep over how it goes.
Medicaid and the spend-down#
Medicaid is the largest single payer of long-term care in the US, and for many families it is the ultimate backstop. The catch is that it is means-tested: you generally qualify only after "spending down" your assets to a very low limit — often around $2,000 in countable assets in many states. In practice that means paying out of pocket until your savings are nearly gone, at which point Medicaid takes over. Official guidance is on the government’s Medicaid resources.
Some families try to plan for this years ahead with legal tools, but the rules are strict — there is a multi-year "look-back" on asset transfers — so it needs a specialist, not a last-minute scramble. Relying on Medicaid is a real option, but it usually means little say over where and how you are cared for, which is why many people prefer to fund at least part of their own care.
Long-term care insurance: how it works#
Long-term care insurance pays a daily or monthly benefit toward care once you can no longer perform a set number of "activities of daily living." Bought at the right age it can shield your savings from the catastrophic scenario, but it has real drawbacks: premiums are high, they can rise over time, and the traditional standalone market has shrunk as insurers found the risk hard to price.
The sweet spot to buy is generally your mid-50s to early 60s — young and healthy enough to qualify at a reasonable premium, but close enough that you are likely to use it. Wait too long and you may be uninsurable or priced out; buy too early and you pay for decades. It is worth getting quotes and comparing before you assume it is simply too expensive.
Hybrid policies and other options#
Because pure long-term care insurance can feel like "use it or lose it," many people now choose hybrid policies that combine long-term care coverage with life insurance or an annuity. If you need care, the policy pays for it; if you never do, your heirs receive a death benefit or you keep the annuity value — so the money is not simply lost. Hybrids cost more upfront, but they remove the biggest psychological objection.
These sit alongside ordinary life insurance in your planning, and which combination fits depends on your age, health and assets. The point is that "insurance or nothing" is a false choice — there is a whole spectrum of products, and a fee-only adviser can help you compare them without a sales agenda.
Self-funding: earmarking your own money#
For those with substantial assets, the simplest plan can be to self-fund — to earmark a slice of your savings and investments specifically for a possible care event and skip insurance altogether. This works if you have enough that a few years of care would not derail you, and it keeps your money flexible if you never need care at all.
It should be built into your broader retirement maths, not bolted on afterward. Working out how much money you need to retire should include a realistic care buffer, and keeping part of your retirement savings earmarked for it means the money is there if the worst happens. Self-funding is really insurance you provide yourself, so the reserve has to be genuinely large.
Family caregiving and its hidden cost#
In reality, most long-term care in the US is unpaid, provided by family members — usually a spouse or an adult daughter. It saves enormous sums, but it is not free: caregivers often cut their hours or leave work, lose income and retirement contributions, and pay a heavy toll in stress and their own health. Counting on family without discussing it is a plan that quietly costs someone dearly.
If family care is part of your expectation, make it an explicit conversation rather than an assumption. Talk about who would provide it, what it would cost them, and how paid help or respite care could share the load. A caregiver who burns out helps no one, and planning for their support is part of planning for your own.
Plan ahead: the documents you need#
Paying for care is only half of planning; the other half is making sure someone can act for you if you cannot. That means putting in place a durable power of attorney for finances and a healthcare proxy or advance directive before there is any question about your capacity. Without them, your family may face a slow, expensive court process just to manage your affairs.
These fit within the broader work of estate-planning basics, and doing them early — while you are healthy — is far easier than in a crisis. The best time to make these decisions is long before you need them, when you can make them calmly and on your own terms rather than under pressure.
When to start planning#
The uncomfortable truth is that long-term care planning is cheapest and easiest exactly when it feels least urgent — in your 50s and early 60s. That is when insurance is affordable and you can still qualify, when you can build a care reserve into your retirement plan, and when the legal documents can be sorted without pressure. Every year you wait narrows your options and raises the price.
You do not have to solve it all at once. Start by learning the real costs, deciding roughly how you would fund a care event, getting a couple of insurance quotes, and putting the key documents in place; official government resources can point you to the programs available in your state. Even a rough plan beats the default, which is to hope it never happens and improvise if it does.
For Canadians#
Canada’s model is different: long-term care is run by the provinces, which subsidize places in long-term care homes but charge an income-tested resident co-payment, alongside publicly funded home care that varies by province. It is more of a public safety net than the US system, but waiting lists and the co-pay mean it is far from free, and many families still top it up privately.
The planning steps are similar: understand your province’s rules and costs, consider private long-term care insurance to cover the gaps, build a reserve into your retirement savings, and get your power of attorney and care directives in place early. The public system carries more of the load than in the US, but personal planning still matters a great deal.
Common mistakes to avoid#
The costliest long-term care mistakes come from assumptions, not from bad luck, and each one is avoidable.
- Assuming Medicare covers it — it doesn’t.
- Waiting until your 70s to plan — insurance may be out of reach.
- Counting on family without asking — it costs them dearly.
- Having no power of attorney — a crisis becomes a court case.
- Ignoring the risk entirely — hoping is not a plan.
- Underestimating how long care lasts — dementia can mean years.
The bottom line#
Long-term care is the risk most retirement plans quietly ignore, yet most people will face some version of it, and the bills are large enough to undo decades of saving. Planning means knowing the real costs, understanding that Medicare will not pay, and choosing how you will fund it — insurance, a hybrid policy, an earmarked reserve, or a clear-eyed plan for Medicaid and family care.
The systems differ enormously by country — a private-insurance model in the US, public dependency programs across much of Europe — but the lesson is the same everywhere: decide how you will handle it while you are still healthy, put the documents in place, and you turn a potential catastrophe into a manageable, planned-for part of growing old.
Frequently asked questions
Frequently asked questions
No, and this is the most important and most misunderstood point in the whole subject. Medicare covers short-term, skilled care — for example a limited period of rehabilitation in a skilled nursing facility after a hospital stay, up to about 100 days — but it does not pay for ongoing custodial long-term care, which is the non-medical help with daily activities like bathing, dressing, eating and moving around that most people actually need as they age. Assuming Medicare will cover a nursing home or years of home care is the mistake that derails the most retirement plans. The programs that do help are Medicaid, which pays for long-term care but only after you have spent down almost all of your assets, and private long-term care insurance, which you buy in advance. Most families end up funding care through a mix of their own savings, insurance, family caregiving, and eventually Medicaid.
Educational content — not personalised financial advice.
Read next
Are Extended Warranties Worth It? What to Know First
Are extended warranties worth it? How service contracts work, why consumer advocates say most are a bad deal, what your manufacturer warranty and credit card may already cover, the auto-warranty robocall scam, when an extended warranty can make sense, and why Europe’s legal guarantee changes the whole calculation.
Pet Insurance: Is It Worth It and How It Works
Pet insurance explained: how the reimbursement model works, what accident-and-illness cover includes, why pre-existing conditions are excluded, deductibles and reimbursement percentages, what it costs, whether it is worth it versus a pet emergency fund, why a dog bite is a homeowners-insurance matter, and how the rules differ abroad.
Final Expense Insurance: How Burial Insurance Works
Final expense insurance explained: how burial insurance works as a small whole-life policy, simplified issue versus guaranteed issue and the graded death benefit, how it differs from a pre-paid funeral plan, what a funeral really costs, your rights under the FTC Funeral Rule, and how the same need is met very differently abroad.