How to File Your Taxes: A Plain-English Guide to Your Tax Return
Filing a tax return is really one act of reconciliation: total up your income, subtract your deductions, work out the tax, and compare it with what was already withheld. Here is how to file your taxes in plain English — whether you have to file, what documents to gather, standard versus itemized, how and where to file, the deadline, and how Canada does it.
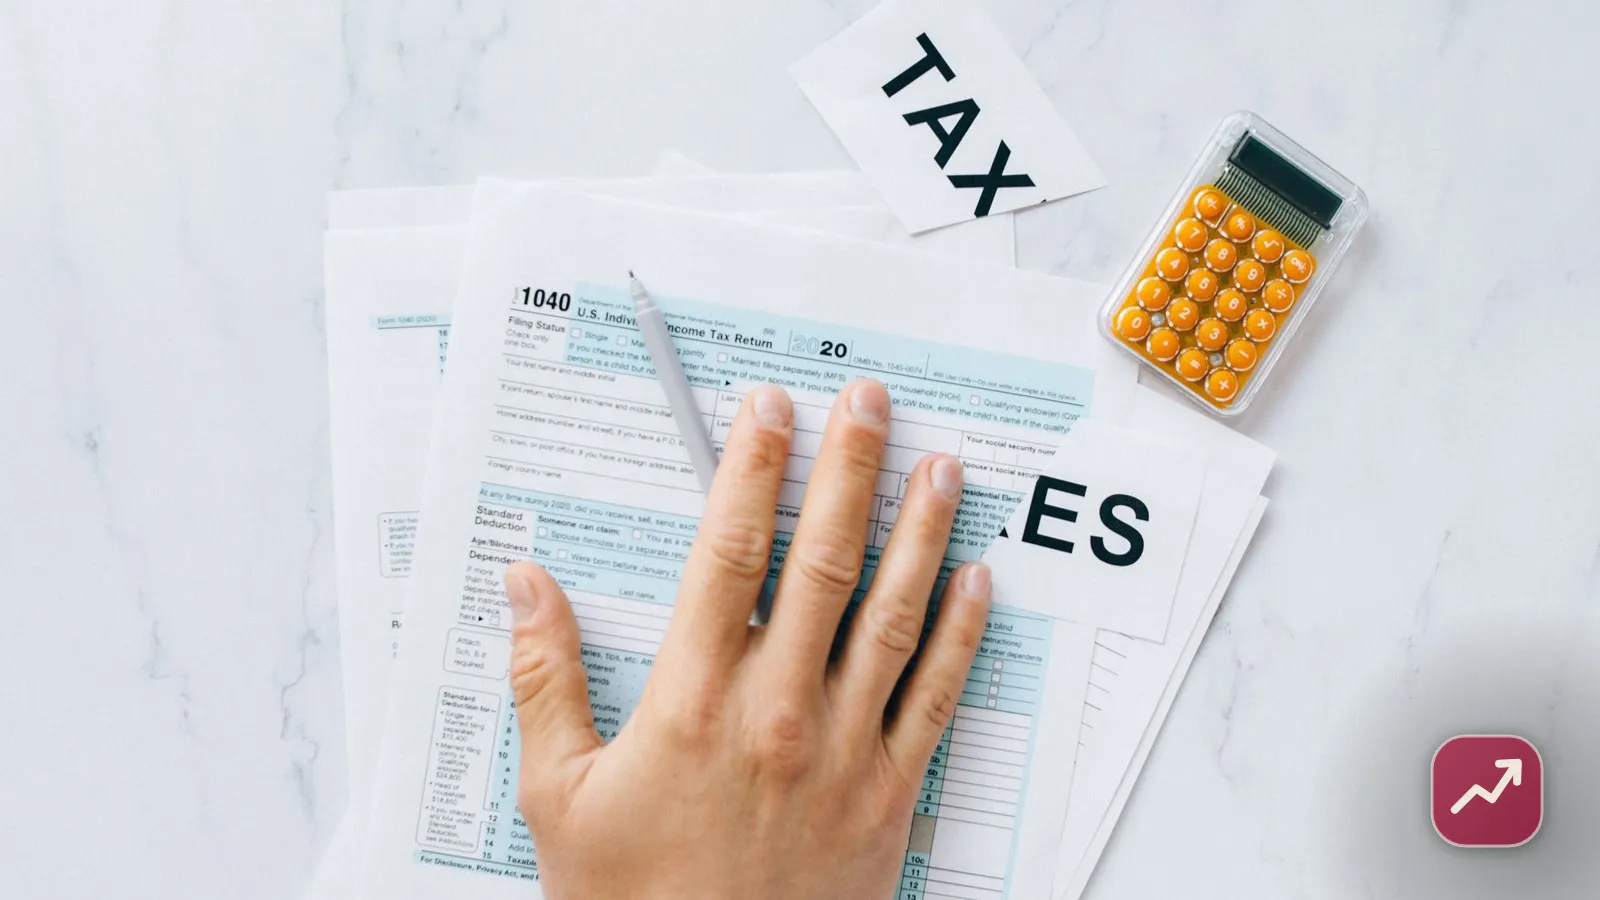
The short answer: reconciling what you owe with what you paid#
Filing a tax return is really an act of reconciliation. Over the year, tax is withheld from your paychecks, and you may owe more on other income. When you file, you add up your total income, subtract the deductions you are entitled to, calculate the tax due, and compare it with what has already been paid. If too much was withheld, you get a refund; if too little, you owe the difference.
In the US, most people file a Form 1040 with the IRS once a year. It sounds daunting, but for a typical employee with a single job it is often straightforward: your employer reports your wages, the software does the math, and you either get money back or send a payment. The complexity comes with extra income, deductions and life changes — which is exactly what this guide will help you handle.
Below we walk through the whole process: whether you even have to file, what documents to gather, the choice between the standard and itemized deduction, how and where to file, the deadline, and what a refund or a balance due means. It also covers how Canada handles the same job. As always, this is general education, not tax advice, and rules change every year — check the current IRS guidance before you file.
- Filing reconciles the year — total tax due versus tax already paid.
- Most employees file a 1040 — often simpler than it looks.
- Refund or balance due — the result of that reconciliation.
- The deadline is usually mid-April — with an option to extend the filing.
Do you even have to file?#
Not everyone is required to file, though many who are not required still should — because that is how you claim a refund of over-withheld tax or valuable credits. Generally, whether you must file depends on your income, age and filing status, with the threshold tied roughly to the standard deduction: earn below it and you often are not required to file, though there are exceptions for self-employment and other cases.
There are good reasons to file even when you do not have to. If tax was withheld from your pay, filing is the only way to get any refund. Refundable credits — for lower-income workers, families with children, education — can put money in your pocket even if you owe no tax. When in doubt, it is usually worth filing, and the IRS guidance on who must file sets out the current thresholds. A quick check there can spare you either an unnecessary filing or, worse, a missed one that later costs a penalty.
Step one: gather your documents#
Filing goes smoothly when your paperwork is ready. Employees receive a W-2 from each employer showing wages and tax withheld. Freelancers and gig workers get 1099 forms for income paid to them. On top of those, you may have forms for interest, dividends, investment sales, retirement distributions, mortgage interest and more — each a piece of the income-and-deductions puzzle.
Keep these together as they arrive early in the year, along with records of anything you plan to deduct. Good records are also what turn your gross pay into an accurate return, the same distinction explained in gross versus net pay. Missing a form is one of the most common reasons a return gets delayed or corrected, so a simple folder — paper or digital — saves real headaches.
Standard versus itemized deduction#
Every filer reduces taxable income with a deduction, and you choose the larger of two options. The standard deduction is a flat amount based on your filing status — simple, and the choice for the large majority of filers. Itemizing means adding up specific deductible expenses — mortgage interest, state and local taxes up to a cap, charitable gifts, large medical costs — and is worth it only if together they exceed the standard amount.
The practical rule is simple: take whichever is bigger. Because the standard deduction is relatively high, most people come out ahead taking it and skip the paperwork of itemizing. But homeowners with a mortgage, big charitable givers or those in high-tax states may do better itemizing. It is one of the levers explored in how to reduce your taxes, and good software will usually test both for you.
How to file: software, Free File and Direct File#
Almost everyone now files electronically, which is faster and more accurate than paper and gets refunds out sooner. There are several routes. Commercial tax software walks you through questions and files for you. The IRS also offers free options: IRS Free File provides free guided software to taxpayers below an income limit, and Free File Fillable Forms are open to everyone — though exactly which free IRS programs are available can change from year to year, so check what is offered for the current season.
Which route fits depends on your situation. A simple return with one W-2 can often be done free in well under an hour; a complex return with a business, rentals or investments may justify paid software or a professional. Whatever you choose, e-file and choose direct deposit for any refund — it is the fastest, safest way, and it avoids the delays of paper returns and mailed checks. The system rests on the same self-assessment idea described in Wikipedia’s overview of US income tax.
The deadline, extensions and paying#
The federal filing deadline is normally mid-April for the previous year’s income. If you cannot file in time, you can request an automatic extension to file — usually to mid-October — but an extension to file is not an extension to pay. Any tax you owe is still due by the April deadline, and interest and penalties accrue on late payments.
So even if you extend, estimate and pay what you owe by April. If you cannot pay in full, file anyway and look into an IRS payment plan; filing on time and paying what you can limits the damage. Missing the deadline entirely, especially when you owe, is the costly mistake — the failure-to-file penalty is usually far steeper than the failure-to-pay one.
Refund or balance due — and what it means#
The bottom line of your return is either a refund or a balance due. A big refund feels like a windfall, but it really means you lent the government money interest-free all year by over-withholding. A balance due means the opposite — you under-withheld. Neither is inherently good or bad; the aim is to land close to zero. Landing near zero means your money worked for you during the year instead of sitting with the government until spring.
If your refund or bill is consistently large, adjust your withholding with a new W-4 at work so your paychecks better match your actual tax. Getting this right keeps more money in your pocket during the year rather than waiting for a refund, and avoids a nasty April surprise — a point consumer guides from the Consumer Financial Protection Bureau make well. It is the same logic as understanding your tax brackets: the more you grasp the math, the fewer surprises.
For Canadians: filing the T1#
Canada works much the same way, with different labels. Individuals file a T1 return with the Canada Revenue Agency, reporting income from T4 slips (employment) and other sources, and claiming the basic personal amount and other credits. The deadline for most people is the end of April; the self-employed get until mid-June to file, though any tax owed is still due in April. It is the same trap as in the US: more time to file is not more time to pay.
Most Canadians file electronically through NETFILE-certified software, and refunds by direct deposit arrive quickly. As in the US, filing is how you claim benefits and credits — several are tied to filing a return even for those with little income. The mechanics differ in the details, but the idea is identical: report the year’s income, claim what you are owed, and settle up with the tax authority.
Mistakes to avoid#
None of these are exotic. They are the ordinary errors that delay refunds or trigger notices, and each one is avoidable.
- Missing a W-2 or 1099 — the IRS already has a copy and will notice.
- Filing on paper when you could e-file — slower and more error-prone.
- Forgetting a refundable credit — that is leaving money on the table.
- Assuming an extension delays payment — it does not; interest still accrues.
- Not adjusting withholding — a huge refund is an interest-free loan you gave.
- Missing the deadline when you owe — the failure-to-file penalty is steep.
The bottom line#
Filing your taxes is, at heart, one reconciliation: total up your income, subtract your deductions, work out the tax, and compare it with what you already paid. For a typical employee it is often quick and free; complexity comes only with extra income and deductions. Gather your documents, choose the bigger deduction, e-file, and mind the April deadline.
Do that and the yearly chore stops being stressful. Aim to land near zero rather than chasing a big refund, adjust your withholding when it drifts, and keep good records for next year. In Canada the forms differ but the job is the same. Treated as the routine reconciliation it is, filing your return becomes a manageable annual habit rather than a dreaded ordeal.
Frequently asked questions
Frequently asked questions
Whether you must file depends mainly on your income, age and filing status, with the threshold tied roughly to the standard deduction: earn below it and you often are not required to file, though there are exceptions, notably for self-employment income. But many people who are not required to file still should, because filing is the only way to get a refund of tax that was withheld from their pay, and to claim refundable credits for lower-income workers, families and students. When in doubt, it is usually worth filing, and the IRS publishes the current income thresholds.
Educational content — not personalised financial advice.
Read next

Moving Abroad: What Happens to Your Taxes, Accounts and Pension
What happens to your money when you move abroad: how tax residence actually works, why US citizens keep filing wherever they live, the exclusion and the credit that prevent double taxation, states that keep taxing former residents, FBAR and Form 8938 reporting, what happens to a 401k or IRA, pensions and health cover across borders, and how leaving works in Canada, Spain, France and Russia.
What to Do If You Can’t Pay Your Taxes: Payment Plans, Penalties and Relief
What to do if you cannot pay your taxes: why filing on time matters more than paying on time, what penalties and interest actually cost, how to set up an IRS payment plan, what happens when the debt is genuinely unpayable, what the tax authority can do without a court order, how to avoid tax-relief scams, and how the same problem is handled in Canada, Spain, France and Russia.
Tax-Deductible Donations: How to Give to Charity Tax-Efficiently
How tax-deductible donations really work: why you usually have to itemize, the new 2026 deduction for non-itemizers, AGI limits, donating appreciated stock to skip capital gains, donor-advised funds, Qualified Charitable Distributions for retirees, and how giving is taxed in Canada and Europe.